 IT
 EN
Land and farms · The guide
Buying and selling a farm.
Land, vineyards and business: what to consider before an important decision.
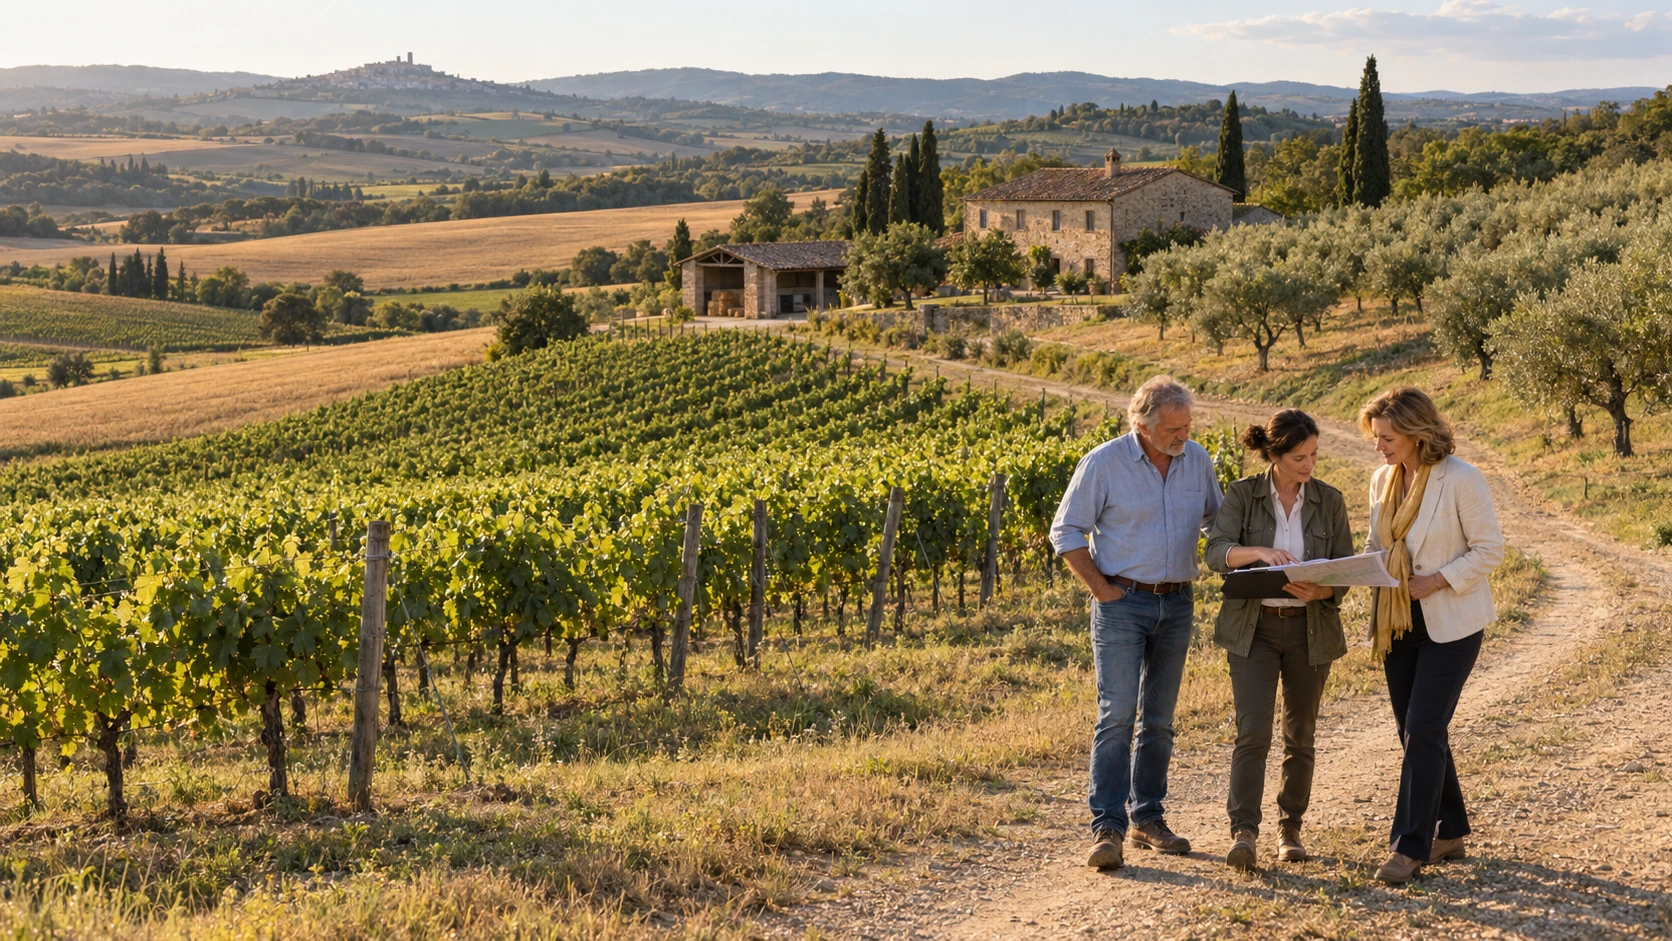
An agricultural estate brings together land, a productive organisation and the identity of its region. A carefully prepared transaction connects these qualities with the documents, third-party rights and commitments that accompany the transfer.
01 · The scope
Land or a business: define what changes hands.
Buying individual plots and buildings differs from acquiring an organised business. The substance of the assets and activities must be examined with the Italian notary and appointed advisers.
The preliminary agreement should identify plots, buildings, installations, equipment, stock, brands and any relationships included. Contracts, staff, receivables and debts require individual examination: their treatment depends on the transaction structure and applicable rules.
Tax treatment follows this analysis. Components and their consideration should be distinguished on a documented basis; a transaction’s label alone does not determine its legal nature.
02 · The vineyards
Check the foundations of productive continuity.
The vineyard register, farm dossier, actual plantings and authorisation records must be considered together. Grape varieties, areas, age, cultivation, production specifications and claimed designations need supporting evidence.
The planting authorisation system operating since 2016 requires checks on holders, validity and conditions for use or succession. Purchasing land does not in itself establish the availability of a replanting authorisation.
EU rules define an abandoned vineyard area, subject to specific exceptions, by the absence of regular cultivation for more than five wine-growing years. Grubbing up such an area does not qualify for the replanting authorisation available for cultivated vineyards. The position requires documentary and field checks; this does not mean every future planting is absolutely prohibited.
A historic or heroic vineyard designation must be checked against the relevant criteria and recognitions. Viticultural permissions do not replace any landscape, environmental or hydrogeological permissions required for works.
03 · Third-party rights
Address agricultural pre-emption early.
Tenants and neighbouring owners may have statutory purchase priority where the legal requirements are met. Status, cultivation, tenancy arrangements, land characteristics and exclusions need case-specific assessment. Merely owning adjacent land is insufficient.
The notary and legal adviser identify eligible parties and arrange the correct content and form of the sale notification, known as denuntiatio. It must communicate the property, purchaser, price and essential terms.
The ordinary exercise period is thirty days following proper notification. In the cases provided by law, missing or defective notification may expose the purchaser to statutory redemption within one year of registration of the sale. Requirements, starting dates and effects require professional assessment.
For bundled land or business sales, the unity of the transaction, independence of individual portions and allocation of relevant prices must be examined. A sale described as a single lot does not automatically settle pre-emption issues.
04 · For sellers
Prepare the handover and preserve value.
Between preliminary agreement, completion and delivery, cultivation, treatments, harvesting, stock, costs and responsibilities should be expressly agreed. The contract should identify who manages production and who is entitled to standing crops.
Public grants and financing may involve continuing commitments, succession approvals and repayment exposure. Review award documents, amounts received and outstanding obligations before selling.
A transfer does not automatically release the seller from existing debts. Non-compete provisions also require careful scope: for agricultural businesses, Civil Code article 2557 applies to connected activities where customer diversion is possible.
For family or generational transfers, price, payments and operational handover should be coherent and documented, alongside dedicated tax and succession advice.
05 · For buyers
Understand liabilities and agree suitable protection.
Review accounting and tax records, staff, contracts, litigation, mortgages and other encumbrances. Buyer liabilities depend on the business and transaction; contractual protections between the parties do not remove third-party rights.
Consider requesting the statutory tax certificate applicable to business transfers. A negative certificate or failure to issue it within the statutory period may have a releasing effect within the applicable limits. Anti-fraud provisions must still be considered; the certificate is not a general guarantee against every liability.
The tax adviser checks the rules effective on the transaction date and appropriate contractual protections. Liability assessment should inform the final price and payment arrangements.
06 · Tax considerations
Check relief eligibility and plan continuing commitments.
Italian small agricultural property relief may apply to agricultural land and its appurtenances acquired by eligible buyers, including qualifying direct farmers and professional agricultural entrepreneurs registered with agricultural social security.
Eligibility is not automatic. The notary and tax adviser assess the buyer, assets and deed structure. Within business transfers, potentially eligible components must be examined separately.
As a general rule, voluntary disposal or ceasing direct cultivation or management within five years can trigger loss of relief, subject to statutory exceptions. The post-acquisition plan should account for these commitments.
The documents to bring to the table.
A working checklist for seller and buyer
- Title history, plot references, boundaries, access, easements and agricultural leases.
- Building planning and cadastral position, land use, water resources and restrictions.
- Farm dossier, vineyard register, authorisations and production records.
- Available accounts, staff, debts, litigation, grants and commitments.
- Pre-emption assessment, transaction scope, price allocation and preliminary terms.
- Cultivation and harvesting plan, inventory and handover record.
ClouCasa®
A transaction prepared with care.
ClouCasa manages the property process and coordinates discussion with agronomists, technical professionals, the notary and legal and tax advisers under the required appointments. Tell us about the estate and your objectives.
Discuss your agricultural project →References and scope
Information updated on 20 October 2026, concerning transactions in Italy. Specialist checks and services depend on the individual appointment. This guide does not replace document review and advice on your circumstances.
- Codice civile · artt. 2135, 2555–2560; L. 590/1965, L. 817/1971; L. 238/2016
- Regolamento delegato (UE) 2018/273 · schedario e superfici vitate abbandonate
- Consiglio Nazionale del Notariato · studio sulla prelazione agraria
- MEF · normativa tributaria e prassi: responsabilità nella cessione d’azienda e piccola proprietà contadina